Owning a car gives you freedom, convenience, and independence, but it also comes with financial responsibilities that extend beyond fuel and maintenance. Accidents, theft, unexpected repairs, and liability claims can quickly create expenses that disrupt even a carefully planned budget.
That’s where Car Insurance becomes essential. A well-chosen policy can help protect your vehicle, finances, and peace of mind when unexpected problems occur. However, understanding coverage options, deductibles, premium calculations, and claims procedures isn’t always straightforward.
This guide explains the fundamentals and advanced considerations of vehicle insurance so you can make smarter, more confident protection decisions.
1. Understanding Car Insurance and How It Works
Vehicle insurance is a financial protection agreement between a policyholder and an insurance provider.
In exchange for regular premium payments, the insurer agrees to cover certain losses or liabilities according to the terms of the policy.
The important word here is certain. Insurance doesn’t automatically pay for every accident, repair, or unexpected expense.
Why Vehicle Insurance Matters
Imagine accidentally damaging another driver’s vehicle during a routine commute.
Without adequate coverage, you could become personally responsible for expensive vehicle repairs, medical expenses, or legal claims.
Insurance helps transfer some of these financial risks to an insurance company.
The National Association of Insurance Commissioners (NAIC) explains that auto policies protect against specified risks while remaining subject to coverage limits, deductibles, and contractual conditions.
This protection becomes particularly valuable when the potential cost of an incident exceeds what a household can comfortably afford.
For example, a relatively minor collision involving a modern luxury vehicle may generate surprisingly expensive repair bills.
Advanced sensors, electronic components, and specialized replacement parts can make damage more costly than it initially appears.
How Insurance Policies Are Structured
Every policy contains several important components.
The premium represents the amount paid to maintain coverage, while the policy limit establishes the maximum amount an insurer will pay for a particular covered loss or liability.
A deductible is the amount the policyholder must pay toward certain covered claims before insurance contributes.
Policies also contain exclusions describing situations that aren’t covered.
Understanding these elements helps drivers avoid incorrect assumptions about their protection.
For instance, purchasing collision coverage doesn’t automatically mean that roadside assistance or rental vehicle reimbursement is included.
Those benefits may require separate endorsements.
Legal Requirements and Financial Responsibility
Insurance requirements vary significantly between countries, states, and territories.
In most U.S. states, drivers must maintain some form of minimum financial responsibility coverage, commonly involving liability insurance.
However, minimum requirements don’t necessarily provide sufficient protection against a serious accident.
A driver who purchases only the legally required coverage may still face substantial personal expenses if damages exceed policy limits.
Vehicle financing creates additional considerations.
Lenders frequently require collision and comprehensive coverage to protect the value of financed or leased vehicles.
Before purchasing a policy, drivers should verify both their local legal obligations and any contractual requirements.
2. Types of Car Insurance Coverage Explained
Insurance products differ based on the risks they protect against.
Understanding the main coverage categories makes it easier to select a policy that matches your vehicle, finances, and driving habits.
Liability Insurance: Protecting Against Third-Party Claims
Liability coverage generally helps pay for injuries or property damage that an insured driver is legally responsible for causing to others.
It commonly includes bodily injury liability and property damage liability.
Bodily injury protection may cover eligible medical expenses and other covered damages involving injured parties.
Property damage liability addresses covered damage to someone else’s vehicle or property.
For example, if you accidentally collide with a parked car, property damage liability may pay for the other vehicle’s repairs within the policy’s limits.
Liability insurance generally doesn’t cover damage to your own vehicle.
That distinction makes it important to consider additional coverage.
Collision Insurance: Coverage for Your Vehicle
Collision coverage generally pays for covered damage to an insured vehicle resulting from a crash with another vehicle or object.
It may also apply when a vehicle overturns.
Imagine losing control on a slippery road and colliding with a roadside barrier.
Collision coverage may help pay for repairs, subject to the deductible and policy conditions.
The insurer generally considers the vehicle’s actual cash value when determining whether repairing it is economically reasonable.
For older cars, the potential insurance payout may be relatively small compared with ongoing premium costs.
Comprehensive Insurance: Protection Beyond Collisions
Comprehensive coverage generally addresses certain losses unrelated to collisions.
Examples commonly include theft, fire, vandalism, hail, falling objects, and damage involving animals.
Suppose a severe storm causes a tree branch to fall onto your parked car.
Comprehensive insurance may cover the resulting damage, subject to the policy’s terms.
It is important to remember that coverage varies.
Certain natural disasters or specific types of damage may be excluded under particular policies.
The NAIC identifies collision and comprehensive coverage as important optional protections, although lenders may require them for financed vehicles.
Uninsured Motorist and Medical Coverage
Uninsured motorist coverage may help protect policyholders when an at-fault driver lacks the required insurance.
Underinsured motorist coverage addresses certain situations where the responsible driver’s liability limits are insufficient.
Depending on local rules and policy terms, medical payments coverage or personal injury protection may help cover eligible medical expenses.
These products aren’t interchangeable.
Eligibility, covered expenses, and legal requirements differ by jurisdiction.
A careful policy review is necessary before assuming that medical costs will be fully reimbursed.
Comparing Major Coverage Types
| Coverage Type | Primary Protection | Typical Example |
|---|---|---|
| Liability | Injury or property damage caused to others | Damaging another driver’s car |
| Collision | Damage to your vehicle from covered collisions | Hitting a roadside barrier |
| Comprehensive | Covered non-collision vehicle losses | Theft, hail, or vandalism |
| Uninsured Motorist | Eligible losses involving an uninsured driver | Injury caused by an uninsured motorist |
| Medical Payments | Eligible accident-related medical expenses | Treatment after a covered crash |
| GAP Protection | Certain loan or lease balance shortfalls | Total loss with an outstanding loan balance |
Actual coverage depends on the insurer, contract, and applicable law.
3. How Car Insurance Premiums and Costs Are Calculated
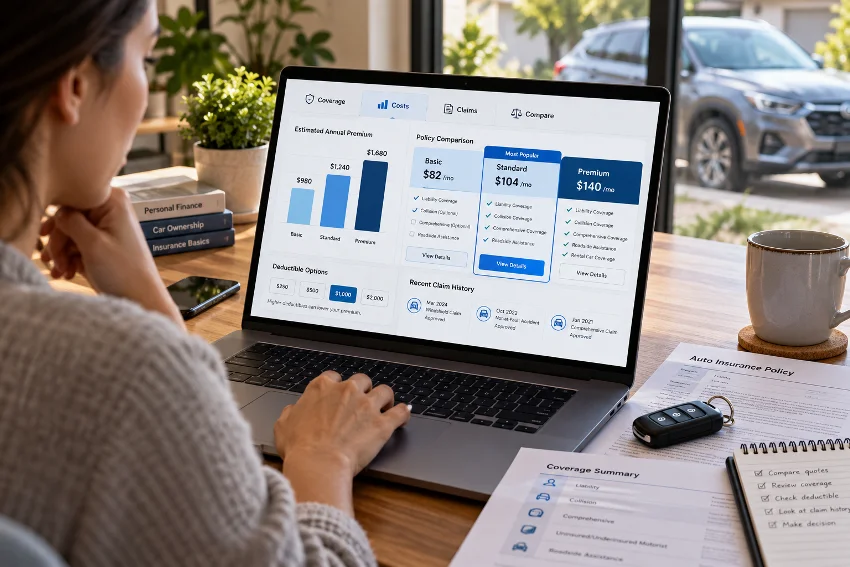
Insurance pricing can seem confusing because two drivers with similar vehicles may recieve very different premium quotes.
This happens because providers consider multiple factors when assessing potential claims and expected costs.
Driving History and Risk Assessment
Driving history is one of the most familiar factors used in premium calculations.
Drivers with recent accidents, serious violations, or limited driving experience may face higher insurance costs.
Insurers use historical information to estimate the likelihood and potential severity of future claims.
However, underwriting models differ between companies.
A driver considered relatively expensive to insure by one provider may receive a more competitive quote from another.
The Insurance Information Institute identifies driving records, vehicle usage, location, coverage levels, and deductibles among common factors influencing premiums.
Vehicle Type, Age, and Repair Expenses
The vehicle itself also plays an important role.
Insurers consider its market value, repair costs, theft exposure, safety characteristics, and historical claims experience.
A vehicle with expensive electronic components may cost more to repair after a collision.
Similarly, certain performance vehicles may be associated with higher expected losses.
The Insurance Institute for Highway Safety uses insurance-loss information to study claim frequency and severity across different vehicle models.
This helps explain why purchasing a relatively inexpensive used vehicle doesn’t always guarantee low insurance premiums.
Location and Annual Mileage
Where you live and drive can influence insurance pricing.
Urban environments may experience greater traffic congestion, accident exposure, or theft activity than less populated areas.
Weather conditions also matter.
Regions exposed to severe storms or frequent hail damage may experience higher comprehensive claims.
Annual mileage provides another measure of driving exposure.
Someone who drives 4,000 miles annually may present different risks from a commuter covering 25,000 miles.
Not every insurer applies mileage adjustments in the same way, making comparisons especially useful.
Understanding Average Insurance Claims
Insurance prices reflect several factors, including the frequency and cost of claims.
The Insurance Information Institute reports the following U.S. average claim amounts for 2024.
These averages don’t represent what every driver will pay or recieve after an accident.
They demonstrate why insurers carefully evaluate both claim frequency and potential financial severity.
For consumers, the practical lesson is simple: the cheapest available policy may not offer enough protection against costly incidents.
4. Deductibles, Coverage Limits, and Policy Exclusions
Understanding deductibles and coverage limits is essential when evaluating insurance affordability.
A low monthly premium may appear attractive until a covered accident produces a substantial out-of-pocket expense.
How Insurance Deductibles Work
A deductible represents the portion of an eligible claim that the policyholder is responsible for paying.
For example, suppose your vehicle sustains $4,000 in covered collision damage.
If your deductible is $500, the insurer may pay $3,500, assuming the claim is approved and no other limitations apply.
If the deductible increases to $1,000, the insurance payment in the same example would be $3,000.
These figures illustrate how deductible selection affects financial responsibility.
Increasing the deductible often reduces premiums because the policyholder accepts a greater share of potential losses.
However, this strategy only makes sense when sufficient emergency savings are available.
Selecting Appropriate Liability Limits
Liability limits determine how much an insurance provider will pay for covered third-party claims.
Some U.S. policies use split limits.
For example, a policy with limits of 100/300/50 generally provides up to $100,000 in bodily injury liability per person, $300,000 per accident, and $50,000 in property damage liability per accident.
These amounts are examples, not universal recommendations.
A serious accident could exceed relatively low coverage limits.
Policyholders should evaluate available assets, potential exposure, financial capacity, and legal requirements when selecting protection.
An insurance professional can help explain how different limits affect premiums and financial risk.
Common Insurance Exclusions
Insurance policies contain exclusions that describe circumstances outside the agreed coverage.
Typical examples may involve intentional damage, unauthorized commercial vehicle use, certain racing activities, or wear and tear.
Mechanical breakdowns are also generally excluded from standard accident insurance.
Coverage may be affected when drivers provide materially inaccurate information or violate specific policy conditions.
However, exclusions vary between insurers and jurisdictions.
Drivers should never assume that one company’s restrictions automatically apply to every policy.
Reading the complete contract helps prevent unpleasant surprises.
Actual Cash Value and Total Loss Settlements
When a car is declared a total loss, insurers commonly calculate compensation using its actual cash value, subject to the applicable policy and law.
This generally reflects the vehicle’s value immediately before the loss rather than its original purchase price.
Imagine buying a car for $30,000 and later experiencing a total loss when its assessed value is $22,000.
The settlement may be based on the lower current value, with any applicable deductible considered.
This can become problematic when the outstanding vehicle loan exceeds the insurance payout.
GAP coverage may help address certain eligible differences between the remaining loan balance and the vehicle’s insured value.
The Consumer Financial Protection Bureau advises comparing GAP insurance costs and eligibility conditions carefully before purchasing.
5. How to File a Car Insurance Claim Successfully
A vehicle accident can be stressful, especially when injuries, unexpected costs, or transportation problems are involved.
Understanding the claims process beforehand makes it easier to respond calmly and document important information.
What to Do Immediately After an Accident
Safety should always come first.
Check for injuries, contact emergency services when necessary, and move to a safer location if doing so is appropriate and lawful.
Avoid creating additional danger while attempting to inspect vehicle damage.
Once the immediate situation is secure, exchange relevant information with other involved drivers.
Photographs of vehicle positions, visible damage, road conditions, and surrounding signs may help document the incident.
Police reports or official incident records may also be required depending on local regulations.
Avoid speculating about fault or making inaccurate statements.
Simply document what occurred as clearly as possible.
Reporting the Incident to Your Insurer
Insurance providers commonly require policyholders to report incidents within specified periods or as soon as reasonably practical.
Contact your provider using its official claims channel.
You may need to submit photographs, incident descriptions, vehicle details, and supporting documents.
The Insurance Information Institute recommends contacting the insurer promptly, understanding filing deadlines, and keeping organized claims records.
Many providers now offer mobile applications that simplify documentation and allow customers to track claim progress.
However, digital convenience doesn’t replace the need for accurate information.
Understanding the Claims Assessment Process
After receiving a claim, an insurer generally investigates the circumstances and evaluates whether the policy covers the reported loss.
This process may involve reviewing photographs, inspecting the damaged vehicle, collecting statements, and evaluating repair estimates.
A claims adjuster may determine the estimated cost of covered repairs.
The insurer then decides whether to approve payment, request additional information, or deny the claim based on the relevant evidence and policy terms.
Settlement timeframes depend on the complexity of the incident and applicable legal requirements.
A straightforward windshield claim may be resolved more quickly than a complicated multi-vehicle accident involving disputed liability.
Handling Denied or Disputed Claims
A denied claim doesn’t always mean the policyholder has no further options.
Begin by requesting a clear explanation of the decision and identifying the policy provisions involved.
Review supporting documents and determine whether important information was missing or misunderstood.
If appropriate, submit additional evidence or use the insurer’s internal appeal process.
Consumers may also contact their relevant insurance regulator or pursue other dispute-resolution options available in their jurisdiction.
Keeping copies of correspondence, estimates, photographs, and decision notices can be particularly valuable.
The objective is to resolve disagreements through accurate documentation and established procedures.
6. Smart Strategies to Reduce Car Insurance Costs
Paying less for insurance doesn’t necessarily require accepting inadequate protection.
Drivers can often improve affordability by comparing providers, reviewing coverage choices, and identifying discounts.
Compare Insurance Quotes Carefully
Insurance companies use different underwriting models and pricing strategies.
As a result, premiums for comparable protection can vary significantly.
Requesting quotes from several providers is one of the simplest ways to identify competitive pricing.
However, meaningful comparisons require identical or closely matched coverage limits, deductibles, and optional benefits.
A policy costing $900 annually isn’t automatically better than one costing $1,100.
The lower-priced option might include substantially weaker protection.
The Insurance Information Institute recommends obtaining at least three quotes and evaluating the provider’s reputation alongside its price.
Consider Available Discounts
Insurers may offer discounts based on driving history, vehicle features, payment arrangements, or customer relationships.
For example, some companies provide savings when customers insure multiple vehicles or combine vehicle and home insurance policies.
Other discounts may apply to drivers who complete approved defensive driving courses.
Low annual mileage may also qualify for reductions.
However, discount availability varies.
The final premium matters more than the number of advertised discounts.
A provider offering fewer promotions may still deliver better overall value.
Review Optional Coverage on Older Vehicles
As vehicles age, their market value generally decreases.
At some point, collision or comprehensive premiums may become relatively expensive compared with the potential insurance payout.
Consider a car valued at $3,500 with substantial annual physical-damage coverage costs.
The owner should evaluate the remaining loan balance, deductibles, potential repair costs, and ability to replace the vehicle independently.
Removing optional coverage can reduce premiums, but it also transfers additional financial risk to the owner.
This decision should never be based on vehicle age alone.
Explore Usage-Based Insurance
Usage-based insurance, often called telematics, adjusts pricing using information about driving behavior or mileage.
Programs may collect data through smartphones, connected vehicles, or dedicated tracking devices.
Depending on the insurer, measurements can include distance traveled, acceleration patterns, braking behavior, and driving times.
The NAIC explains that these programs may use behavioral information to calculate more individualized premiums.
However, drivers should understand the potential privacy implications.
Before enrolling, ask what information is collected, whether premiums can increase, and how driving data may be stored or shared.
A discount isn’t necessarily worthwhile if the program’s conditions don’t fit your preferences.
7. Choosing the Right Car Insurance Policy for Long-Term Protection
The most effective insurance strategy considers more than the initial premium.
Your vehicle’s value, household finances, driving patterns, and coverage requirements may change over time.
Reviewing insurance regularly helps keep protection aligned with current circumstances.
Evaluate the Insurer’s Financial Stability
Insurance companies promise to pay eligible claims when specified losses occur.
Financial stability therefore matters.
Consumers can review insurer financial ratings, regulatory information, and available complaint records.
A company offering an unusually low premium may not deliver the best overall experience if its customer service is consistently poor.
Claims communication, repair coordination, and dispute handling can become especially important after a serious accident.
Match Coverage to Your Personal Risk
Different drivers need different levels of protection.
A commuter driving through congested urban roads may face different exposure than someone using a car occasionally.
Similarly, a driver financing a new vehicle has different contractual requirements from someone owning an older vehicle outright.
The Consumer Financial Protection Bureau encourages comparing insurance costs and coverage before financing a vehicle.
This can prevent unexpectedly high transportation expenses after purchasing a car.
Review Your Policy Before Renewal
Insurance renewal provides an opportunity to reassess protection and costs.
Changes in driving mileage, vehicle value, household drivers, or financial circumstances may justify updating the policy.
Drivers should also verify that personal information remains accurate.
Incorrect vehicle usage descriptions or outdated driver details can create administrative problems.
Comparing alternatives before renewal may reveal better coverage or more competitive premiums.
However, avoid creating an unintended coverage gap when switching providers.
Understand Emerging Insurance Technologies
Modern vehicles increasingly incorporate advanced driver-assistance systems, connected technology, and sophisticated electronic components.
These developments can affect both accident risk and repair costs.
The same technologies that help drivers avoid certain collisions may be expensive to repair after damage.
Insurance companies are also exploring increasingly sophisticated pricing and claims assessment tools.
Consumers should remain informed about how technology affects coverage, premiums, and personal information.
The goal is to make confident decisions rather than automatically choosing the newest or cheapest product.
A little extra research today can prevent significant financial difficulties tomorrow.
Choosing the right Car Insurance requires understanding coverage types, premium factors, deductibles, exclusions, and the claims process. The most affordable policy isn’t always the one offering the strongest financial protection.
Take time to compare providers, review your coverage limits, and identify opportunities for savings. With consistant planning and carefull evaluation, you can protect your vehicle, manage unexpected costs, and drive with greater confidence.